Quick Answer
Pay Off Debt Fast With Low Income clearing your balances through small consistent extra payments, negotiated lower rates, hardship programs, and windfall allocation rather than large monthly payments. Even $50 to $150 a month in extra payments, combined with a rate reduction, can cut years off a typical payoff timeline.
In this guide, you will learn 8 realistic tactics for a tight budget, a low-cost versus high-cost options comparison, and the 5 money traps that prey on low-income borrowers.
Introduction
Most debt advice assumes you have hundreds of spare dollars a month. “Just pay an extra $500!” is easy to say from a comfortable salary. If your household brings in $35,000 to $45,000 a year, that advice is not just unhelpful, it is insulting.
Here is the truth nobody tells you: low income does not disqualify you from getting out of debt. It just changes the tools. High earners win with big payments. Low-income households win with smart payments: negotiated rates, hardship programs, fee waivers, and small extras applied with discipline.
I have watched single parents, gig workers, and retirees on fixed incomes clear five-figure debts with the 8 tactics below, applied month after month. This guide is the tight-budget companion to our complete how to pay off debt guide.
What Does Paying Off Debt With Low Income Actually Mean?
It means accepting a different definition of “fast.” For a household earning $38,000 a year with $13,000 in debt, fast means 24 to 36 months instead of the 10-plus years minimum payments would take. That is still years of interest erased.
The low-income payoff approach has three pillars. First, shrink the cost of the debt itself through negotiation, hardship programs, and rate reductions, because a lower rate does the work your paycheck cannot. Second, manufacture a small but sacred extra payment, $50 to $150 a month, from budget surgery and windfalls. Third, protect the plan with a starter emergency fund so one car repair does not restart the whole cycle.
Notice what is not on the list: miserable extreme frugality or burnout second jobs. Sustainability beats intensity. A plan you can live with for 30 months beats one you survive for 3.
The Lean Ladder Method: Your Framework
I call this the Lean Ladder Method because it borrows the structure of our Debt Freedom Ladder and rebuilds every rung for a tight budget. Each tactic below is one rung. You do not need all eight on day one. Start with tactics 1 through 3, which cost nothing and can cut your interest rate this week, then climb as your plan stabilizes.
The method attacks the rate before the balance: a 5-point rate reduction on a $6,000 balance saves roughly what an extra $40 a month would, and the phone call is free.
8 Clever Tactics for a Tight Budget
Tactic 1: Negotiate every interest rate by phone
Call each creditor and ask for a lower APR. Use this script: “I have been a customer for X years, I always pay on time, and I am working hard to pay down my balance. Can you lower my interest rate?” Then stop talking and let them answer.
A drop from 26.99% to 19.99% on a $5,000 balance saves about $350 a year in interest without you paying a dollar more. If the first representative says no, ask for a supervisor or the retention department. One call per card, once a year, is the highest-return phone call in personal finance.
Tactic 2: Ask about hardship programs before you miss a payment
Creditors have formal hardship programs that temporarily lower your rate, waive fees, or reduce your minimum, often for 6 to 12 months. The key word is “before”: call while your account is current and ask what programs exist.
Hardship programs are not advertised, but they are real, and using one is far better than missing payments and triggering penalty APRs near 30%. A temporary 9.99% hardship rate for a year can save more interest than months of extra payments.
Tactic 3: Get fees waived and cards downgraded
Late fees run $30 to $41 each and annual fees $95 and up. Call and ask: waive the late fee (first-time requests are often granted), remove the annual fee, and downgrade to a no-annual-fee card.
Every fee you eliminate is money that now attacks principal instead of padding the issuer’s revenue. On a tight budget, $200 a year in waived fees is functionally identical to a $17-a-month raise dedicated to debt.
Tactic 4: Build a $50 to $150 sacred extra payment
Forget the “$500 extra” advice. Your target is a small, non-negotiable extra payment that survives real life. Find it with a 30-minute audit of the last 60 days: subscriptions, delivery orders, automatic charges, canceled or paused ruthlessly.
Common finds: an unwatched $16 streaming service, $60 a month in delivery fees, a $25 subscription box. Most households find $80 to $150 without touching anything that matters. That money gets a name, your debt payment, and it leaves your account the day after payday.
Tactic 5: Allocate every windfall by the 50% rule
Tax refunds, bonuses, sold furniture, cash-back rewards: send at least half of every unexpected dollar to your target debt. The average federal tax refund runs into the thousands, enough to delete an entire small balance.
The 50% rule works because it is not deprivation. You keep half, guilt-free, and the debt gets half. People who send 100% of windfalls to debt usually rebel by month three. People who send half sustain it for years.
Tactic 6: Use community resources without shame
Nonprofit credit counseling agencies offer free budget reviews and debt management plans with reduced rates. Community action agencies and local nonprofits often run financial assistance and free tax preparation programs.
These resources exist for exactly your situation, and using them is smart, not shameful. The National Foundation for Credit Counseling’s member agency network connects you with accredited nonprofit counselors for a free initial session, and starting there costs nothing (NFCC, 2026).
Tactic 7: Add one small income stream, temporarily
You do not need a second career. You need a 6-to-12-month income bump dedicated entirely to debt: sell unused items, pick up gig work, offer a skill you already have, or ask about overtime.
Earmark 100% of this income for the target debt. The temporariness is the point: “I am doing this for 8 months to kill the store card” is sustainable in a way that “I work two jobs now” is not. When the target debt dies, you can stop, and the rolled payment keeps working without the extra hours.
Tactic 8: Run a zero-based mini budget every payday
Every payday, assign every dollar a job before it gets spent: bills, groceries, gas, debt extra, and a small personal allowance. When the dollars are assigned, spending stops.
This takes 15 minutes per payday with a notebook or a free app. The magic is the personal allowance line, even if it is only $20. Budgets without any fun money get abandoned. Budgets with a little fun money get followed, and a followed budget is what funds tactic 4 month after month.
Low-Cost vs. High-Cost Payoff Options
Some options cost nothing and save thousands. Others target low-income borrowers because they are profitable. Know the difference.
| Option | Upfront cost | True cost on $10,000 debt | Verdict for tight budgets |
|---|---|---|---|
| Negotiating your APR by phone | Free | Saves $300 to $600 a year in interest | Do this first, today |
| Nonprofit credit counseling (NFCC member) | Free session; DMP fees vary, often waived | Reduced rates save thousands over the plan | Best free professional help available |
| Creditor hardship program | Free | Temporary low rate saves hundreds | Ask before you miss a payment |
| Balance transfer card (0% promo) | 3 to 5% transfer fee | About $300 to $500 fee, then 0% interest | Good only with 670+ credit and a finish-before-deadline plan |
| Debt consolidation loan | Origination fee 1 to 8% | About $100 to $800 plus interest | Worth it only if the rate beats your average APR |
| Debt management plan (nonprofit) | Setup plus monthly fees, often reduced | About $500 to $1,500 over the plan | Solid option when you need structure |
| For-profit debt settlement | 15 to 25% of enrolled debt | $1,500 to $2,500 on $10,000, plus credit damage | Avoid; the CFPB warns these programs carry severe risks (CFPB, 2024) |
| Payday or title loan | $15 to $30 per $100 borrowed | Can exceed 300% APR; a $500 loan can cost $1,500+ | Never; this is a debt trap, not a tool |
The pattern is clear: the cheapest options are the phone calls and the nonprofit help, while the most expensive are marketed hardest to struggling borrowers. The FTC’s credit and debt guidance explains how to spot debt relief scams before you sign anything (FTC, 2026).
5 Money Traps to Dodge
Low income makes you a target. These five traps are engineered to profit from desperation. Dodge all of them.
Trap 1: Payday and title loans
A $500 payday loan with a $75 fee due in two weeks sounds manageable until you roll it over. Rolled over a few times, that $500 costs more than $1,500 at effective APRs above 300%. No payoff plan survives this. If you are considering one, call a nonprofit credit counselor first.
Trap 2: For-profit debt settlement companies
They promise to cut your debt in half, charge 15 to 25% of your enrolled debt, and often tell you to stop paying creditors while they “negotiate.” Your credit craters and forgiven debt can be taxed as income. Legitimate help comes from nonprofit agencies.
Trap 3: Raiding retirement accounts
Cashing out a 401(k) triggers income tax plus a 10% early withdrawal penalty if you are under 59 and a half. A $10,000 withdrawal can easily cost $3,500 in taxes and penalties on day one.
Trap 4: “Credit repair” services with upfront fees
Federal law bars credit repair companies from charging before they perform services, and none can legally remove accurate negative information. Disputing errors is something you can do yourself for free.
Trap 5: Minimum-payment comfort
Paying the minimum feels responsible, and on a tight budget it can feel like all you can do. But minimums on a $6,000 balance at 24% APR stretch past a decade and more than double the cost. A lower rate plus a $50 extra beats minimums by years.
Pro Tips From a Decade of Payoff Plans
Pro Tip: Write down every “no” and call back in 90 days. A “no” today can become a “yes” next quarter with a longer on-time streak. Keep a log: date, who you spoke to, what they offered.
Pro Tip: Automate the extra on payday, not month-end. Money left at month-end gets spent. Money moved the day after payday never tempts you. Set the extra payment to transfer automatically within 24 hours of your paycheck landing.
Pro Tip: Celebrate the rate cut, not just the payoff. When a creditor drops your APR from 26.99% to 19.99%, calculate the annual savings and acknowledge the win. These invisible victories are what keep a 30-month plan alive.
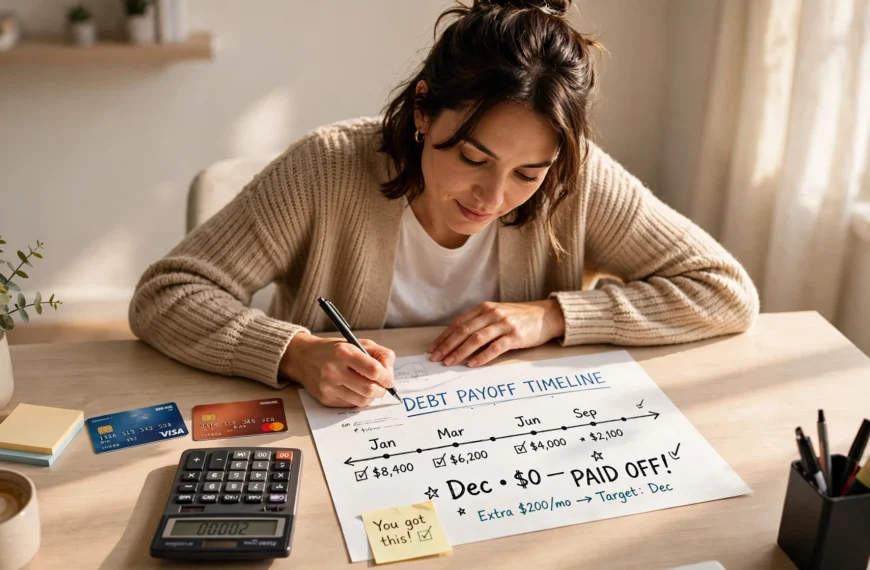
Pro Tip: Keep one “debt-free date” visible. A sticky note on the bathroom mirror with your target month works better than any app. You see it twice a day, every day, and it quietly steers a hundred small decisions toward the plan.
Mini Case Study: How the Alvarez Family Cleared $13,400 on $41,000 a Year
The Alvarez family, two hourly workers in Arizona earning about $41,000 combined, carried $13,400 across three cards at 24.99% to 29.99%. Minimums totaled $335 a month, and the minimums-only path stretched over 12 years with more than $15,000 in interest.
Two phone calls got one card dropped from 29.99% to 21.99% and an $89 annual fee waived on another. A hardship program cut the third card to 12.99% for 12 months. Those three free calls saved roughly $900 in first-year interest.
Then the budget audit found $120 a month: a canceled subscription stack, switched phone plan, and meal planning that cut takeout from weekly to monthly. Total monthly debt payment became $455. They chose the snowball order from our debt snowball calculator guide, smallest balance first.
Month 11 brought a $2,900 tax refund; the 50% rule sent $1,450 to the target card, killing it outright. By month 26, two cards were dead and the full $455 was hammering the last one, with the final payment landing in month 31.
Total interest paid: about $3,400 versus $15,000-plus on minimums, and their credit scores rose roughly 90 points combined. Thirty-one months on $41,000 a year, with no second jobs. The free phone calls did the heavy lifting their paychecks could not.
If you want to model your own card timelines precisely, our credit card payoff calculator guide shows the 7 inputs that make the math honest.
Frequently Asked Questions
Can you really pay off debt fast with a low income?
Yes, with a realistic definition of fast. A household earning under $45,000 can typically clear $10,000 to $15,000 in consumer debt in 24 to 36 months using negotiated rates, hardship programs, and $100 to $150 in monthly extras. That beats the decade-plus minimums path by years, with interest savings in the thousands.
What is the first thing to do when you cannot afford minimums?
Call your creditors before you miss a payment and ask about hardship programs. Then contact a nonprofit credit counseling agency for a free session. Do both before considering anything involving fees or new borrowing.
Are debt management plans worth it on a low income?
A nonprofit DMP typically reduces your rates to around 8 to 10%, consolidates everything into one payment, and runs 3 to 5 years, with modest fees often waived for hardship. Compare its total cost against your current path first, and verify the agency is an NFCC member.
Should I get a second job to pay off debt faster?
Only as a short-term, targeted tactic. Six to twelve months of extra income aimed at one specific debt can shave a year off your plan, but chronic overwork leads to burnout spending that erases the gains. Tactic 7 works when it has an end date and a single target.
How do I negotiate a lower credit card APR?
Call the number on the back of your card, mention your on-time history and loyalty, and ask directly for a lower rate. If they decline, ask about hardship programs or a supervisor, and call back in 90 days. The call is free.
Is a balance transfer card a good idea with low income?
Only if two conditions hold: your credit score qualifies you (usually 670 or higher), and you have a written plan to clear the transferred balance before the 0% period ends. The 3 to 5% transfer fee still applies. If you cannot realistically finish in time, the remaining balance reverts to a high rate and you have paid a fee for nothing.
What should I do with my tax refund?
Send at least half to your current target debt, per the 50% rule. A typical refund can erase months of payments in one stroke. Keep the other half guilt-free: for savings, necessities, or a small reward. The split is what makes the habit sustainable year after year.
How do I stay motivated for a 30-month payoff plan?
Track visible progress: monthly balance updates, win dates on your calendar, and a folder of killed-debt confirmations. Re-run your payoff numbers quarterly. Motivation follows visible progress, so make the progress visible.
Conclusion
Paying off debt fast with low income is not about finding money you do not have. It is about the Lean Ladder Method: negotiate rates for free, enroll in hardship programs before trouble hits, waive the fees, build a small sacred extra payment, split every windfall, use the community resources built for exactly this, add temporary income with an end date, and budget every payday.
Start today with tactic 1. One phone call, ten minutes, potentially hundreds of dollars a year in saved interest. Then climb one rung at a time.
About the Author
Laiba is a personal finance writer with 10 years of experience helping Americans build realistic debt payoff plans. She specializes in turning intimidating money math into step-by-step systems real households can follow, and her work has guided thousands of readers from minimum payments to zero balances.

 By

 By